For practices
How percentage of collections pricing works for billing
Two billing companies can quote the same percentage and cost you very different amounts. How the fee math works, and what to check before you sign.
2 minute readBy the Fieldstone Billing teamUpdated
Many billing companies charge a percentage of collections. It sounds simple, but two companies quoting the same percentage can end up costing you very different amounts, and the reasons are usually sitting in the contract.
The basic math
Your fee equals your collections multiplied by your rate. If the contract sets a monthly minimum, compare the minimum with that figure, and you pay whichever is higher.
What a monthly minimum does to your rate
A minimum sets a floor under the fee. When collections are low, the minimum applies instead, which means your effective rate is higher than the quoted one. To find your effective rate, divide the total fee by your collections. Run this for your lowest collection months as well as your average months, since those are the months when a minimum costs the most.
Say two companies quote you the same percentage, and one of them adds a minimum that happens to match what that percentage comes to in a normal month. Most of the year the two invoices look the same. Then your physician takes three weeks off in August, collections fall by half, and the fee from the company with the minimum stays where it was. You’ve paid the same fee on half the money, so your effective rate for that month is double what you were quoted.
Questions to ask before you sign
- What counts as collections? Is it insurance only, or patient payments too? Does it include payments on claims from before the company started?
- What’s included? Denials, posting, statements, reporting and coding review are often handled differently.
- What costs extra? Ask about setup fees, statements, clearinghouse fees and credentialing.
- How do you leave? Look at the notice period and at what happens with open claims.
- Who holds the money? Payments should normally go directly to your practice account.
The first question catches people out. If older claims count, you could end up paying the new company a percentage on a payment for a claim your last biller had already finished working.
Where percentage pricing is restricted
It isn’t allowed everywhere or in every arrangement. Some states restrict percentage billing, and Medicare and Medicaid limit percentage fees when a billing company receives the payment. Payer contracts and fraud and abuse rules can come into it too, particularly when a company has a financial interest in what gets billed. Ask your adviser if you’re unsure. A good billing company should be willing to discuss it and to offer another structure where needed.
Looking past the rate
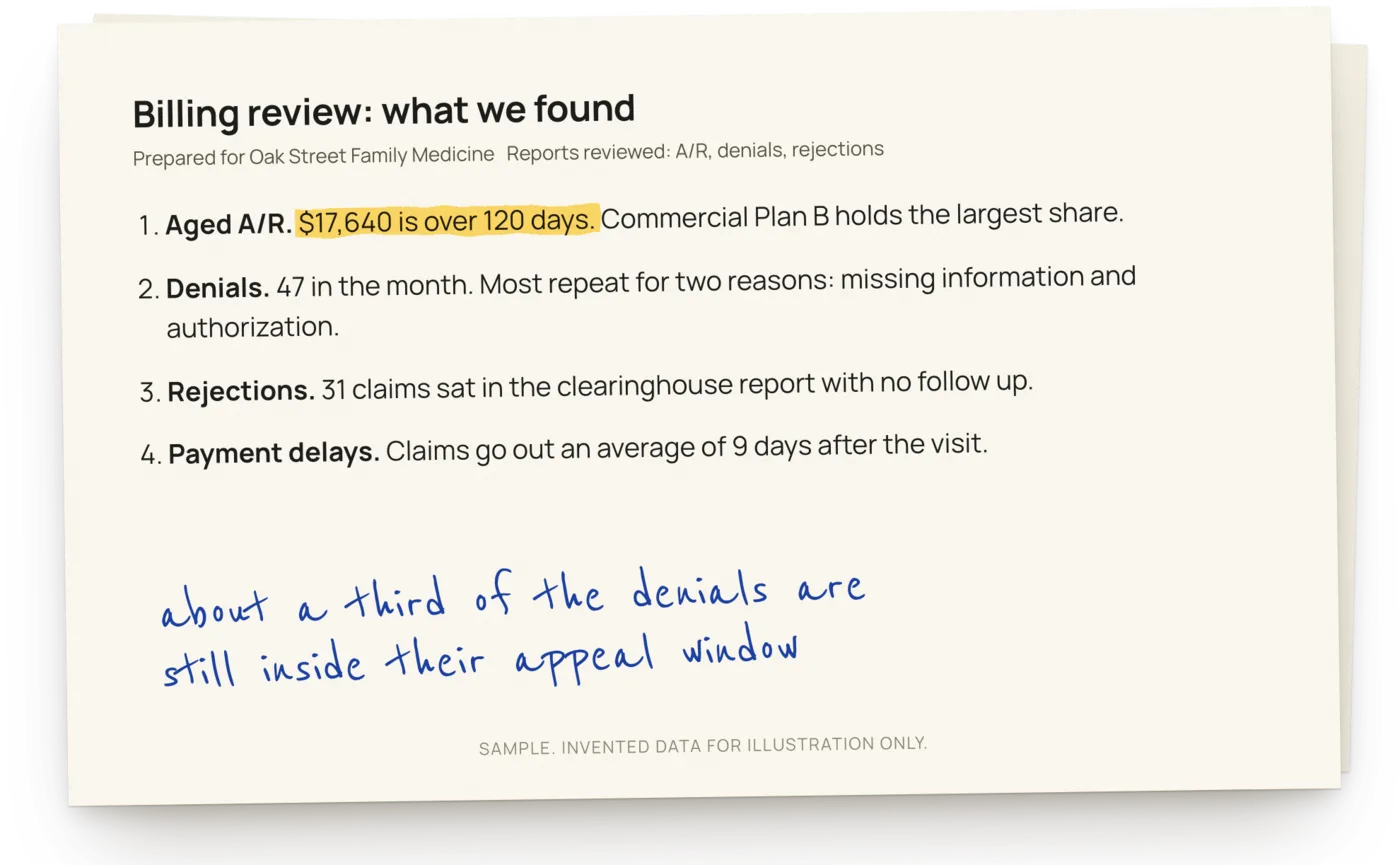
A low rate on a poorly worked account can cost you more than a higher rate on a well worked one, because unworked denials don’t show up on the invoice. Nobody sends you a bill for the CO-16 that never got fixed, and you just don’t get paid for that visit. So ask how the company will measure and report results, and weigh that alongside the fee. You can also read how we price medical billing.