For billing company owners
How to sell a small or one person billing company
Most advice on selling a billing company assumes staff and a big client list. Here's what's different when it's you and a handful of accounts.
3 minute readBy the Fieldstone Billing teamUpdated
If you run billing from a spare room with six or seven clients, a lot of the advice about selling a business won’t fit you. It talks about management teams and audited financials, and you’ve got a filing cabinet and a phone that clients still call on Sundays.
You can still sell. The buyers are different, though, and so is what they’re paying for.
Who actually buys a company this size
Brokers often aren’t an option at this end. Synergy Business Brokers, for example, says it focuses on companies with annual revenue of $700,000 or more, and plenty of owners never get close to that.
The likelier buyer is another billing company. An HBMA article by a business broker put it plainly in 2021, saying most buyers of medical billing companies are other medical billing companies. For them, your clients are the attraction, since they already have the staff and software to do the work. That’s also who you may already know, from a local association meeting or from a client who switched years ago.
What a buyer sees when they look at you
They’ll worry about one thing more than the others, which is that you’re the whole business. Clients trust you personally, the procedures live in your head, and nobody else has ever spoken to that one payer rep who actually calls back.
So most of what you can do to get ready is about making the accounts easier to hand over. Our guide to making the company less dependent on you goes through it, and even a few months of that work helps.
Why these deals usually pay over time
You’ll probably be paid over time, at least in part, and tied to whether clients stay. That HBMA article gives an example of 80% of the price paid at closing with the rest paid as clients remain, and it says you could expect 50 to 60% to be paid that way if one client makes up a lot of your revenue. It’s one broker’s example from 2021, for companies of all sizes, so don’t treat it as what you’ll be offered. A very small client list tends to carry more risk for a buyer, because losing one client hurts more.
Read up on revenue share and seller financing before you talk numbers, and on the earnout terms worth negotiating before you sign.
A short list to start with
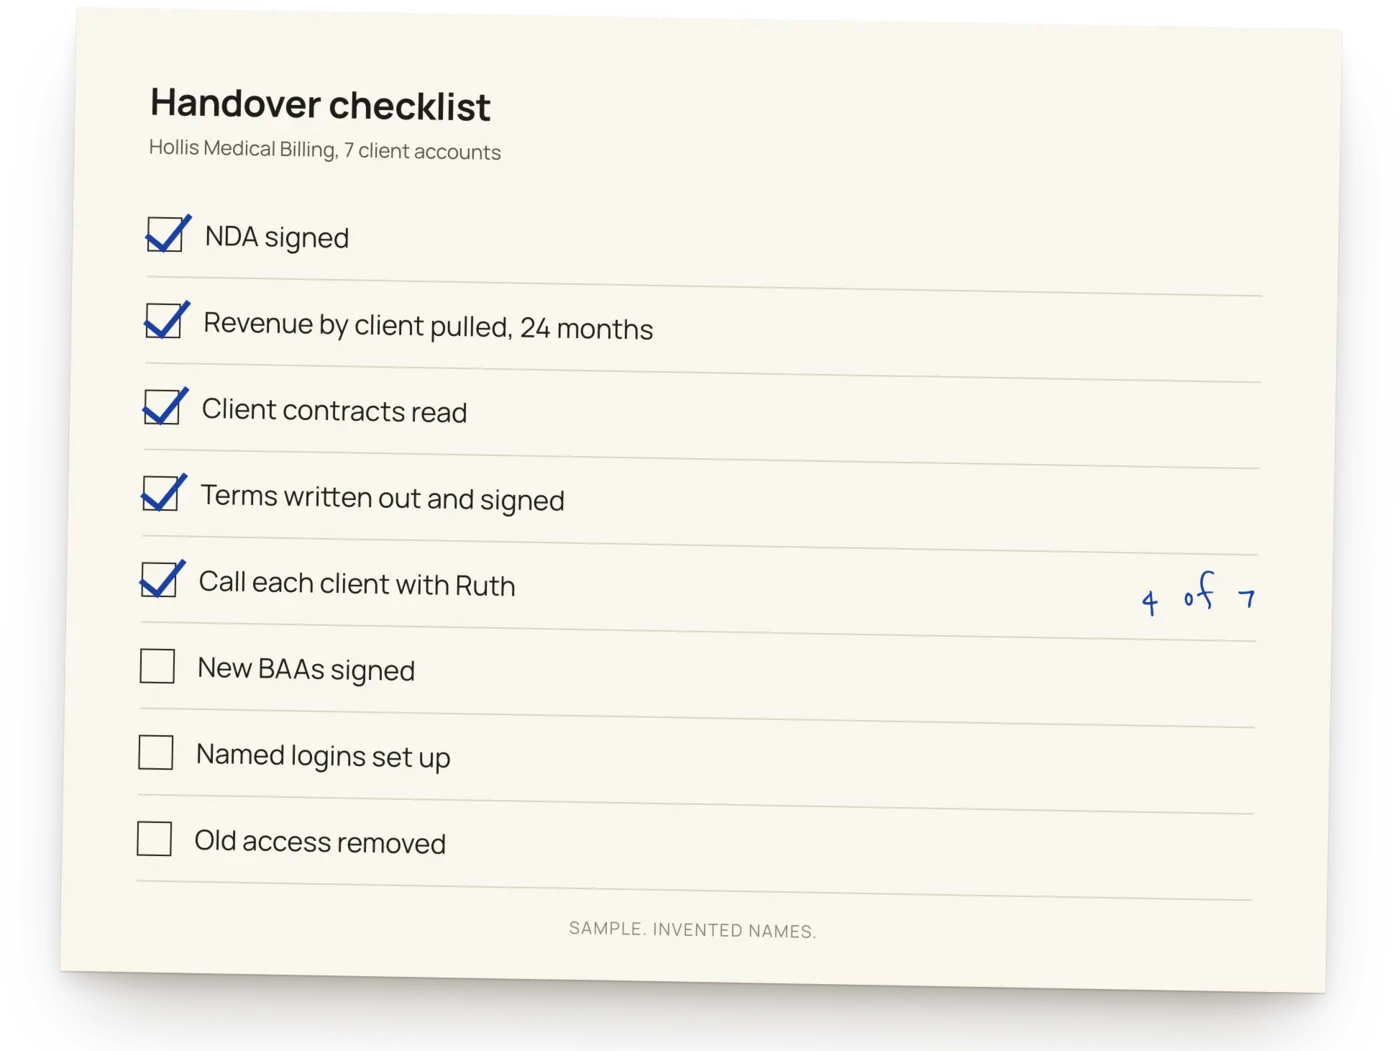
You can do all of this in a weekend or two, and you don’t have to tell anyone you’re doing it.
- Write down what each client paid you over the past 12 months, and check it against your deposits.
- Find every client contract. If there isn’t one, note that too. Our guide to client contracts explains why it comes up.
- List every login you use, and whose name it’s in.
- Write one page on each client covering their EHR, their payers, who to call and what’s odd about them.
- Decide roughly when you’d like to stop, and how many months you could stay on to help.
Be realistic about timing
A small company won’t have many interested buyers, so finding the right one can take a while. If your health or family has already set the date, say so at the start, because a buyer can plan around a short handover far better than a surprise.
And if nobody suitable turns up, you’ve still got options. You can refer clients to someone you trust, or wind the business down with enough notice that nobody misses a filing deadline.
Fieldstone may be a buyer in a sale like this, so read this guide with that in mind. It's general information, and it isn't legal or tax advice.