For billing company owners
A retirement checklist for billing company owners
What to do in the years and months before you retire from your billing business, so you still have options for your clients and your company.
2 minute readBy the Fieldstone Billing teamUpdated
Most billing owners think about retirement for a long time before they do anything about it, and the ones with the most options are usually those who started preparing early. This list runs backward from your date. If you’ve only got a year, start at the one year mark and pick up what you can from the earlier section as you go.
Two to three years out
Most of this is cleanup, and it’s far easier while nobody is looking at your books.
- Decide what a good outcome looks like for you, including the money, the timing, how clients are treated and how much you still want to work.
- Get client contracts in writing where they’re missing, and check the notice and assignment terms on the ones you have.
- Make sure each client has a current Business Associate Agreement.
- Separate personal and business finances, so that revenue is easy to verify.
- Start introducing clients to another person on your team, if you have one.
One year out
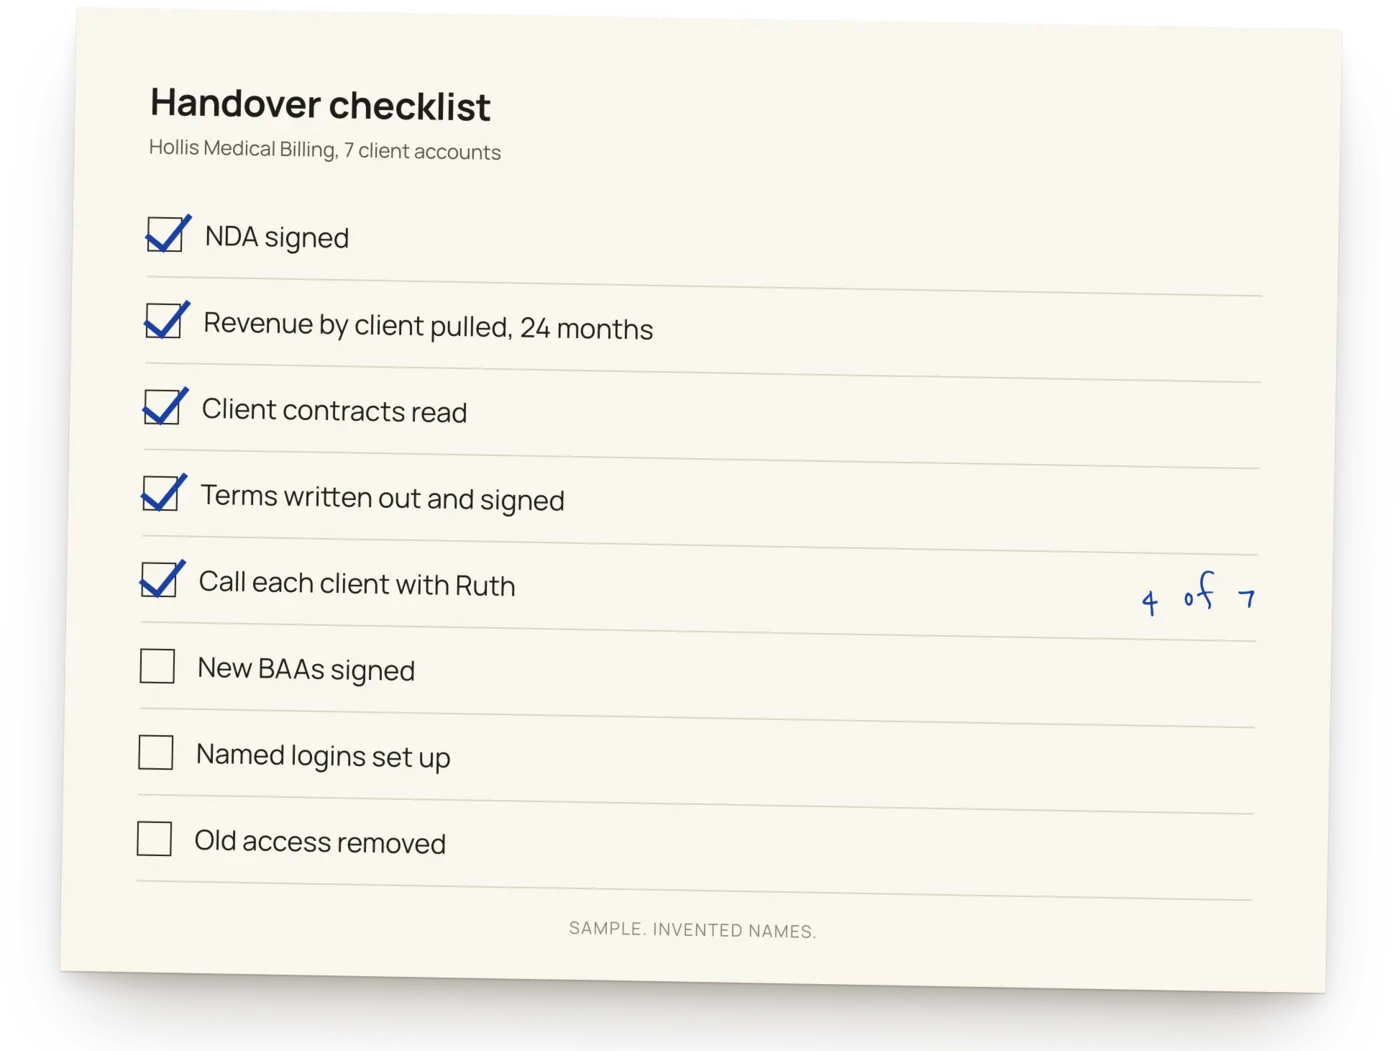
- Organize 24 months of revenue by client, supported by deposits and invoices.
- Write down how the work gets done, including each client’s quirks. If one office only answers its fax on Tuesdays, that belongs in there.
- List all your systems and logins, along with who owns them.
- Speak with an attorney and a tax adviser about structures and timing.
- Decide if you want to sell everything, or just part of your client list.
Six to twelve months out
- Begin confidential conversations with possible buyers, using a non disclosure agreement before sharing client names or numbers.
- Compare structures, since revenue share and seller financing divide risk differently.
- Agree on who tells clients, and when.
- Talk to any staff when the time is right, and agree on what happens to their roles.
During the handover
- Introduce the new team personally.
- Stay available for an agreed period.
- Check that patient data access is transferred properly, and remove old access.
- Keep reading the reports that support any payments you’re owed. If you’re being paid over time, those reports are how you’d notice clients leaving or a buyer falling behind.
If you have to leave sooner
Life doesn’t always give you three years, and health or family can bring the date forward. You can still have useful conversations, but the handover becomes the main issue, so tell a potential buyer your true timeline at the start.
If nobody buys
You can also refer clients to a trusted company, or wind down over time with enough notice. Check your contracts first. Whichever way you go, your clients need enough time to avoid missed filing deadlines, because a clinic that gets two weeks’ notice may not have a new biller working before claims start running into a short commercial limit. We’ve written up how to close a billing business in more detail.
Who wrote this
We’re looking to acquire small billing businesses, so Fieldstone isn’t a neutral source. Use this checklist with your own advisers. If you’d like to talk, see how selling to us would work.
Fieldstone may be a buyer in a sale like this, so read this guide with that in mind. It's general information, and it isn't legal or tax advice.